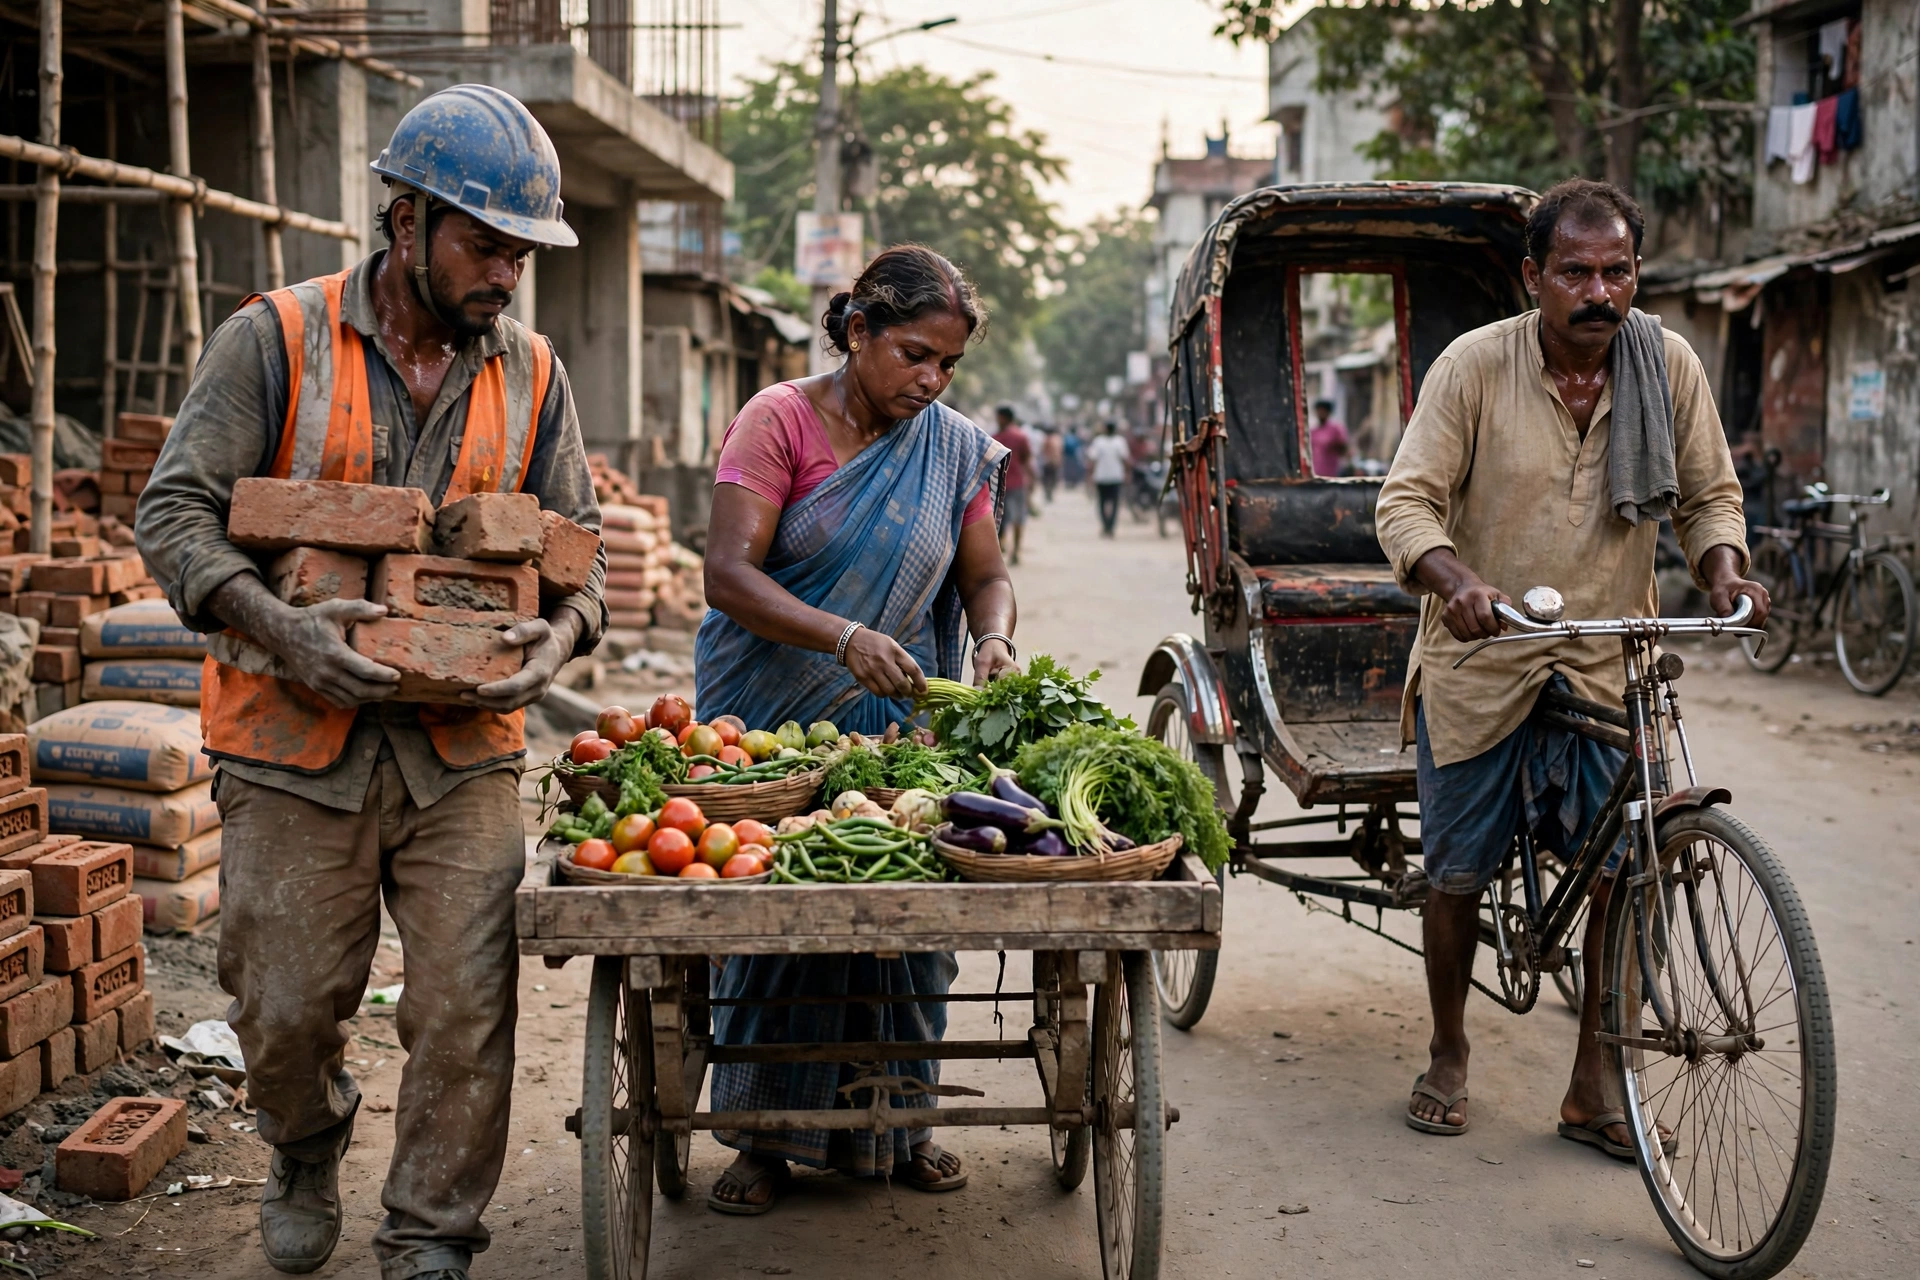
Street vendors, rickshaw pullers, domestic workers, labourers — ₹3,000/month assured pension after 60. And the government matches your contribution rupee for rupee! That is PM Shram Yogi Maandhan — the pension scheme for unorganised workers.
Launched in 2019, the scheme asks just ₹55/month at 18 — the government adds ₹55 too. In this detailed guide, we explain in simple language — what PM-SYM is, the full contribution chart, who is eligible, how to enroll (CSC/online), what the spouse gets, and the 5 mistakes that stop pensions. At the end, 24 essential questions are answered.
PM-SYM: Key Facts at a Glance
| Point | Details |
|---|---|
| Scheme | Pradhan Mantri Shram Yogi Maandhan (PM-SYM) — Labour Ministry |
| Launched | 2019 (interim Budget); LIC is pension fund manager |
| Pension | ₹3,000/month (from age 60, lifelong assured) |
| Contribution | 50:50 — government matches what you pay |
| Minimum | ₹55/month (joining at 18) |
| Eligibility | Unorganised workers, 18–40 years, monthly income up to ₹15,000 |
| Enroll | maandhan.in or CSC centre |
Scheme Launch: The 2019 Story
In the February 2019 interim Budget, the Finance Minister announced PM-SYM — the first big pension scheme for the country’s 42 crore unorganised workers. The scheme launched on 15 February 2019.
The goal: Organised-sector employees get EPFO pension — but street vendors, labourers and domestic workers had no old-age support. PM-SYM filled this gap.
LIC was made the pension fund manager — so the money stays safe and the pension is guaranteed. Enrollment was given to CSC — reach to every village.
What Is PM-SYM?
PM-SYM — a voluntary, contributory pension scheme for unorganised-sector workers. On a 50:50 basis — whatever you contribute, the Central Government matches it. ₹3,000/month assured pension from age 60.
The scheme is run by the Ministry of Labour & Employment; LIC is the pension fund manager; enrollment via CSC.
Contribution Chart: How Much Do You Pay?
| Joining age | Your contribution | Government’s contribution | Total/month |
|---|---|---|---|
| 18 years | ₹55 | ₹55 | ₹110 |
| 25 years | ₹80 | ₹80 | ₹160 |
| 30 years | ₹105 | ₹105 | ₹210 |
| 35 years | ₹150 | ₹150 | ₹300 |
| 40 years | ₹200 | ₹200 | ₹400 |
Golden rule: The earlier you join, the less — ₹55 at 18, ₹200 at 40.
Full Chart: Contribution at Every Age
Per the official chart, the monthly contribution at every age (your share; the government matches it):
| Age | Contribution | Age | Contribution |
|---|---|---|---|
| 18 | ₹55 | 30 | ₹105 |
| 20 | ₹61 | 32 | ₹120 |
| 22 | ₹68 | 34 | ₹136 |
| 24 | ₹76 | 36 | ₹160 |
| 26 | ₹85 | 38 | ₹180 |
| 28 | ₹95 | 40 | ₹200 |
The math: Someone joining at 18 pays a total of ~₹27,720 over 42 years — and gets ₹36,000 pension every year after 60. Meaning the entire contribution is recovered in one year of pension — the rest of life is profit.
How Does Auto-Debit Work?
- At enrollment, auto-debit consent is taken from the bank account
- The contribution auto-deducts on a fixed date every month — no worry about forgetting
- If the account has no balance, the debit fails — repeated failures can make the account dormant
- Dues can be paid later with penalty — the account becomes active again
Tip: Always keep 2–3 months’ contribution extra in the account — even one failed debit spoils the record.
Who Is Eligible?
- Unorganised workers — street vendors, rickshaw pullers, domestic workers, construction workers, farm labourers, tailors, beedi workers, brick kiln workers
- Age 18–40 years; monthly income up to ₹15,000
- Aadhaar + savings bank account (Aadhaar-linked)
- Not in EPFO/ESIC/NPS; not an income taxpayer
How to Enroll?
Method 1 (CSC): Visit the nearest Common Service Centre — give Aadhaar + bank passbook — enrolled in 15 minutes — pension card instantly.
Method 2 (Online): maandhan.in — mobile + OTP login — fill Aadhaar, bank details — set up auto-debit.
Which Workers Are Covered? (Full List)
PM-SYM’s definition of unorganised worker is very broad:
- Street vending: Vegetable/fruit sellers, tea-snack carts
- Transport: Rickshaw/auto drivers, porters
- Domestic: Domestic workers, cooks, nannies
- Construction: Masons, labourers, painters
- Agriculture: Farm labourers, animal husbandry
- Artisans: Tailors, cobblers, barbers, washermen, beedi makers
- Others: Brick kiln workers, fishermen, leather workers, incense/matchstick makers
Conditions: Not in EPFO, ESIC or NPS; monthly income up to ₹15,000; not an income taxpayer.
Want to Exit? (Exit Rules)
- Before 10 years: Only your contribution back with interest — not the government’s share
- After 10 years, before 60: Your contribution + interest back (government’s share stays in the pension fund)
- After 60: Pension starts — no question of withdrawal
- On death: Spouse continues or withdraws the full corpus + interest
Advice: Don’t exit midway — the real benefit of the pension comes only after 60.
What Does the Spouse Get?
- Death before 60: The spouse can continue the scheme, or withdraw the full corpus + interest
- Death during pension: The spouse gets 50% family pension (₹1,500/month) for life
PM-SYM vs Atal Pension
- PM-SYM: Only unorganised workers; government matches 50%; pension fixed at ₹3,000
- APY: Anyone (non-taxpayer); no government match; choose pension ₹1,000–₹5,000
PM-SYM vs APY vs NPS: Which to Choose?
| Point | PM-SYM | APY | NPS |
|---|---|---|---|
| For whom | Unorganised workers | Anyone (non-taxpayer) | Anyone |
| Government contribution | 50% match | No | No |
| Pension | ₹3,000 fixed | Choose ₹1,000–₹5,000 | Market-linked |
| Minimum | ₹55/month | ₹42/month | ₹500/year |
| Best for | Unorganised workers | Small savers | Long-term investors |
Rule: PM-SYM and APY cannot be taken together — choose one. For unorganised workers, PM-SYM is better (the government adds 50%).
Full Enrollment Walkthrough (at CSC)
1. Go to the nearest CSC — carry your Aadhaar card + bank passbook.
2. The operator enters your mobile number on maandhan.in and verifies the OTP.
3. Aadhaar e-KYC — identity confirmed via fingerprint/OTP.
4. Fill bank details — account number, IFSC — give auto-debit consent.
5. Enter the nominee’s (spouse/child) name.
6. Pay the first contribution in cash — the pension card prints instantly.
Time: The whole process takes 15–20 minutes — no fees.
How Is the Pension Paid? (After 60)
- At 60, the ₹3,000/month pension starts — lifelong guaranteed
- Money comes every month via DBT to the bank account — no forms, no running around
- On the pensioner’s death, the spouse gets ₹1,500/month family pension
- Life certificate must be given every year in November — from bank/CSC
Note: If the life certificate is not given, the pension can stop — do it every November.
2 Success Stories
Ramu (rickshaw puller, UP): Joined at 25 — ₹80/month contribution. At 60, a ₹3,000/month pension — no need to pull a rickshaw in old age.
Meena (domestic worker, MP): Joined at 30 — ₹105/month. After her husband’s death, the family pension supported her — the children’s education didn’t stop.
Lesson: Small contribution, big support — the earlier you join, the bigger the benefit.
5 Big Mistakes — Never Make Them
- Trying to join after 40 — eligibility ends.
- Not keeping balance in the account — auto-debit fails.
- Applying while in EPFO/NPS — not eligible.
- Income above ₹15,000 — not eligible.
- Paying an agent — enrollment at CSC is free.
Beware of Fraud
If anyone demands fees or OTP for PM-SYM, it is fraud. Enroll only on maandhan.in or at a CSC.
Frequently Asked Questions (FAQs)
Q1: How much pension do I get?
A: ₹3,000/month (from age 60).
Q2: How much must I pay?
A: ₹55–₹200/month (by age); the government matches it.
Q3: Who is eligible?
A: Unorganised workers aged 18–40 (income up to ₹15,000).
Q4: Can EPFO members join?
A: No.
Q5: Where do I enroll?
A: On maandhan.in or at a CSC centre.
Q6: What does the spouse get?
A: 50% family pension (₹1,500/month).
Q7: Death before 60?
A: Spouse continues or withdraws corpus + interest.
Q8: Can income taxpayers join?
A: No.
Q9: When do I get the pension card?
A: Instantly after the first contribution.
Q10: Is this site governmental?
A: No — GramSuvidha is a private information portal. Verify on maandhan.in.
Q11: How much total if I join at 18?
A: About ₹27,720 over 42 years — and ₹36,000 pension every year.
Q12: What if auto-debit fails?
A: Pay the dues with penalty and the account becomes active again.
Q13: Can I take both APY and PM-SYM?
A: No — choose one of the two.
Q14: What do I get exiting before 10 years?
A: Only your contribution with interest — not the government’s share.
Q15: Are domestic workers eligible?
A: Yes — domestic workers, nannies, cooks are all eligible.
Q16: How do I get the pension card?
A: Instantly after the first contribution — download the PDF from CSC/portal.
Q17: Can I join after 40?
A: No — eligibility is only 18 to 40 years.
Q18: What is LIC’s role?
A: LIC is the pension fund manager — it keeps the money safe and pays the pension.
Q19: When must I give the life certificate?
A: Every year in November — from a bank or CSC.
Q20: Is the scheme still running in 2026?
A: Yes — PM-SYM continues with the same rules; enrollment is open on maandhan.in.
Q21: Is there any fee for enrolling at a CSC?
A: No — PM-SYM enrollment at CSC centers is free; do not pay any fee.
Q22: Is the pension taxable?
A: Pension may fall under income tax rules — usually no tax applies within the senior citizen exemption limit.
Q23: Can the monthly contribution increase?
A: No — the contribution fixed at enrollment stays constant based on your age.
Q24: Will the pension continue if I move to another state?
A: Yes — pension comes via DBT directly to your account, so it continues even after moving states.
Important Links
- Maandhan portal: maandhan.in
Disclaimer: GramSuvidha is a private information portal (not a government website). The information above is based on official sources — rules can change, so please confirm on the official portal.