Want to start a small business but short on funds? PM Mudra Yojana gives collateral-free loans from ₹50,000 to ₹20 lakh. But: ₹20 lakh is not for everyone, rates are not fixed, and there is no subsidy — this guide covers the verified truth from mudra.org.in and PIB.
We explain the four categories (Shishu, Kishore, Tarun, Tarun Plus), eligibility, how to apply, and fraud warnings. 25 essential questions answered at the end.
Key Facts
| Point | Info |
|---|---|
| Scheme | PMMY — Central Govt |
| Launched | 8 April 2015 |
| Loan | ₹50K–₹20L (by category) |
| Collateral | None — CGFMU cover |
| Subsidy | None (permanent) |
| Apply | Bank branch or udyamimitra.in |
What Is PMMY?
Launched 8 April 2015. Loans to non-corporate, non-farm micro/small enterprises for manufacturing, trading, services, and allied agriculture (poultry, dairy, beekeeping). Motto: “Funding the Unfunded.”
MUDRA Doesn’t Lend Directly
MUDRA Ltd. is a refinance institution — loans come from banks/NBFCs/MFIs. Apply at a branch or on udyamimitra.in.
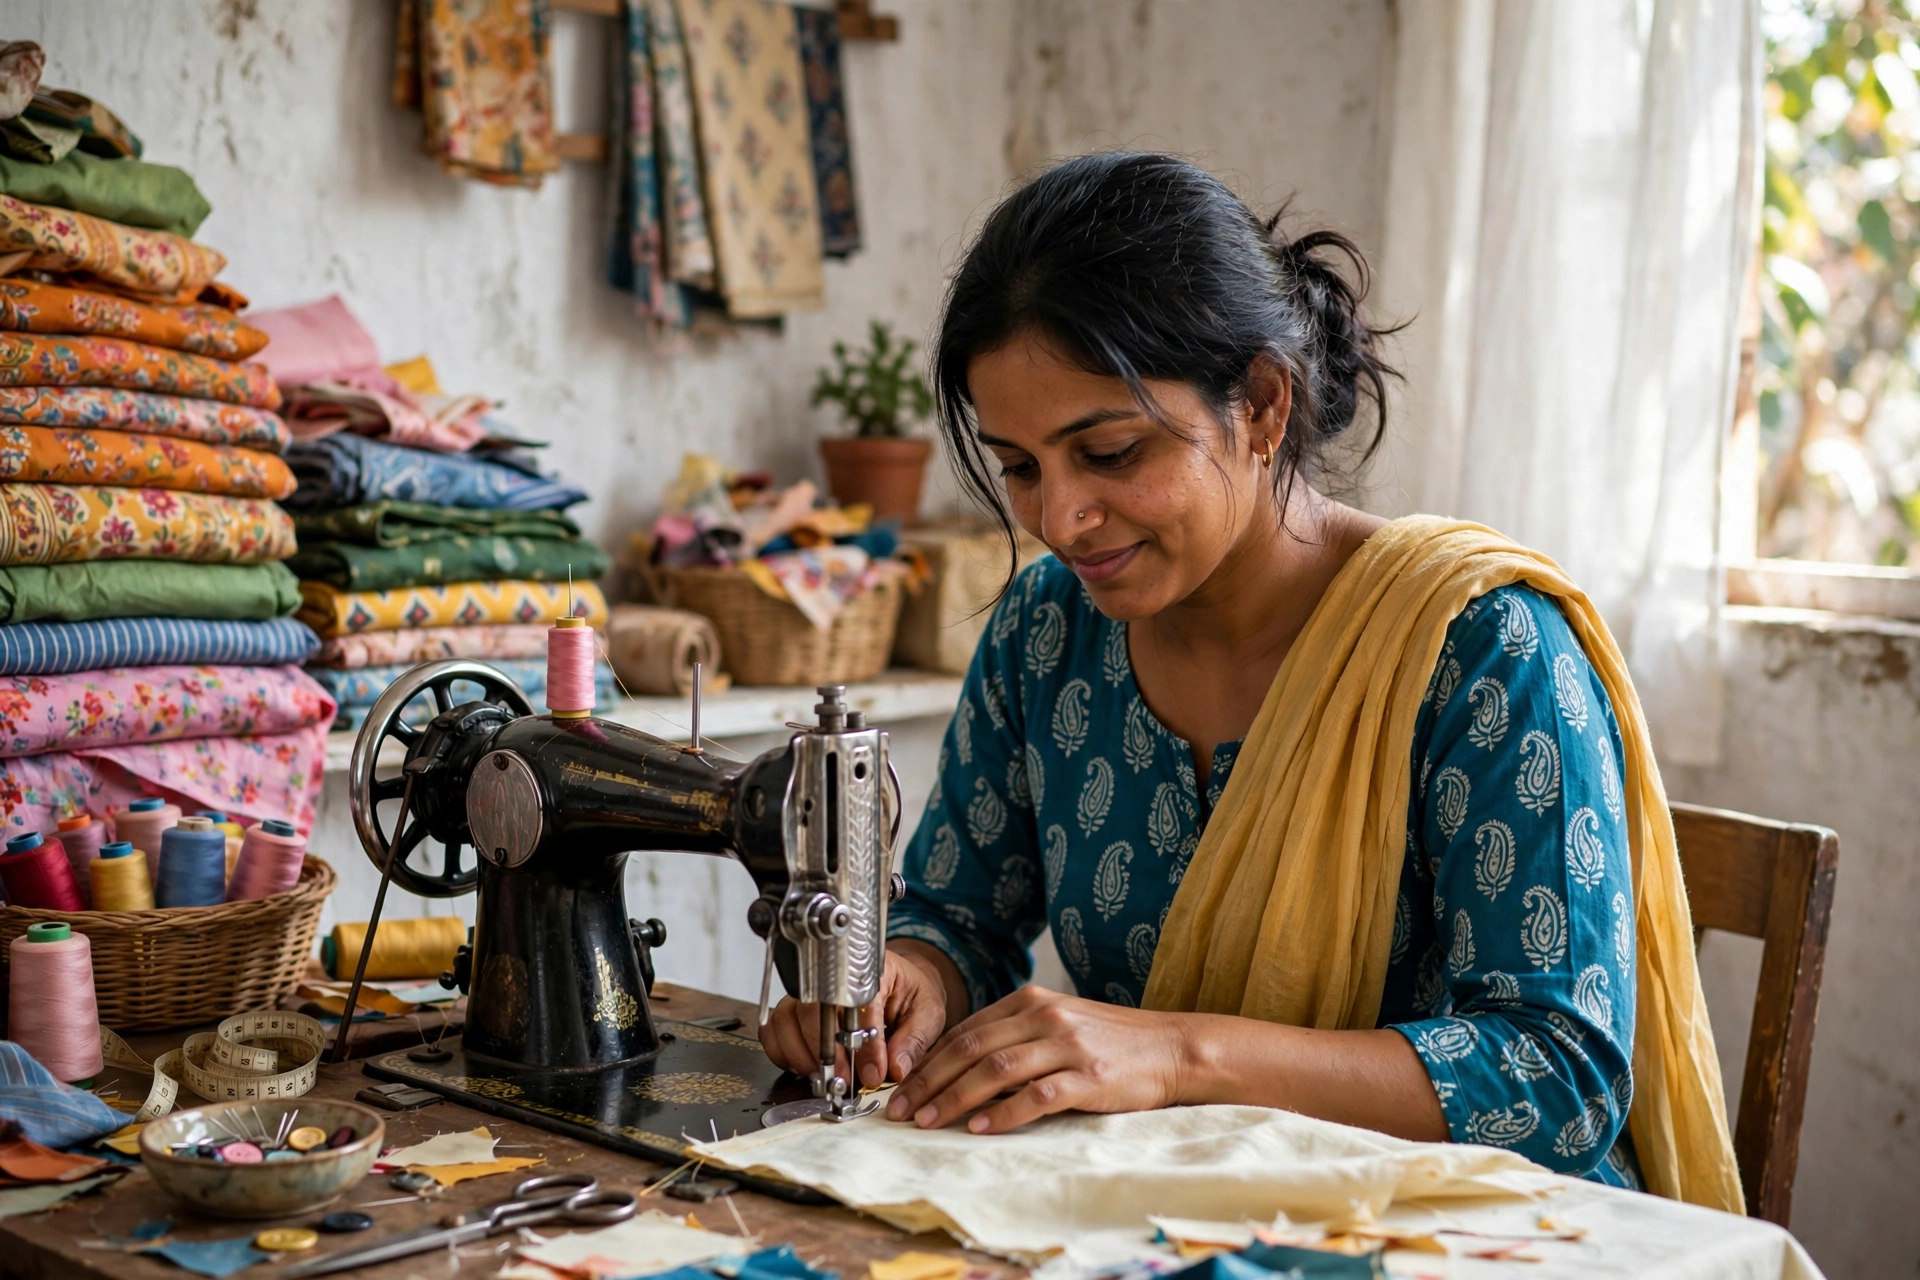
Four Categories
| Category | Amount |
|---|---|
| Shishu | Up to ₹50,000 |
| Kishore | ₹50K–₹5L |
| Tarun | ₹5L–₹10L |
| Tarun Plus | ₹10L–₹20L (only after repaying Tarun) |
Tarun Plus Truth
- Announced: Budget 2024-25 (23 July 2024)
- Effective: 24 Oct 2024
- Only for those who repaid a Tarun loan
- CGFMU guarantee applies
Rates NOT Fixed
Government doesn’t fix rates. Per PIB, each lender decides under RBI guidelines. Ask your bank.
No Subsidy
No permanent subsidy exists. “35% subsidy” is false. Only exception: temporary 2% Shishu subvention in FY 2020-21 (COVID relief, one year).
CGFMU (2016)
Collateral-free loans backed by CGFMU, set up 2016.
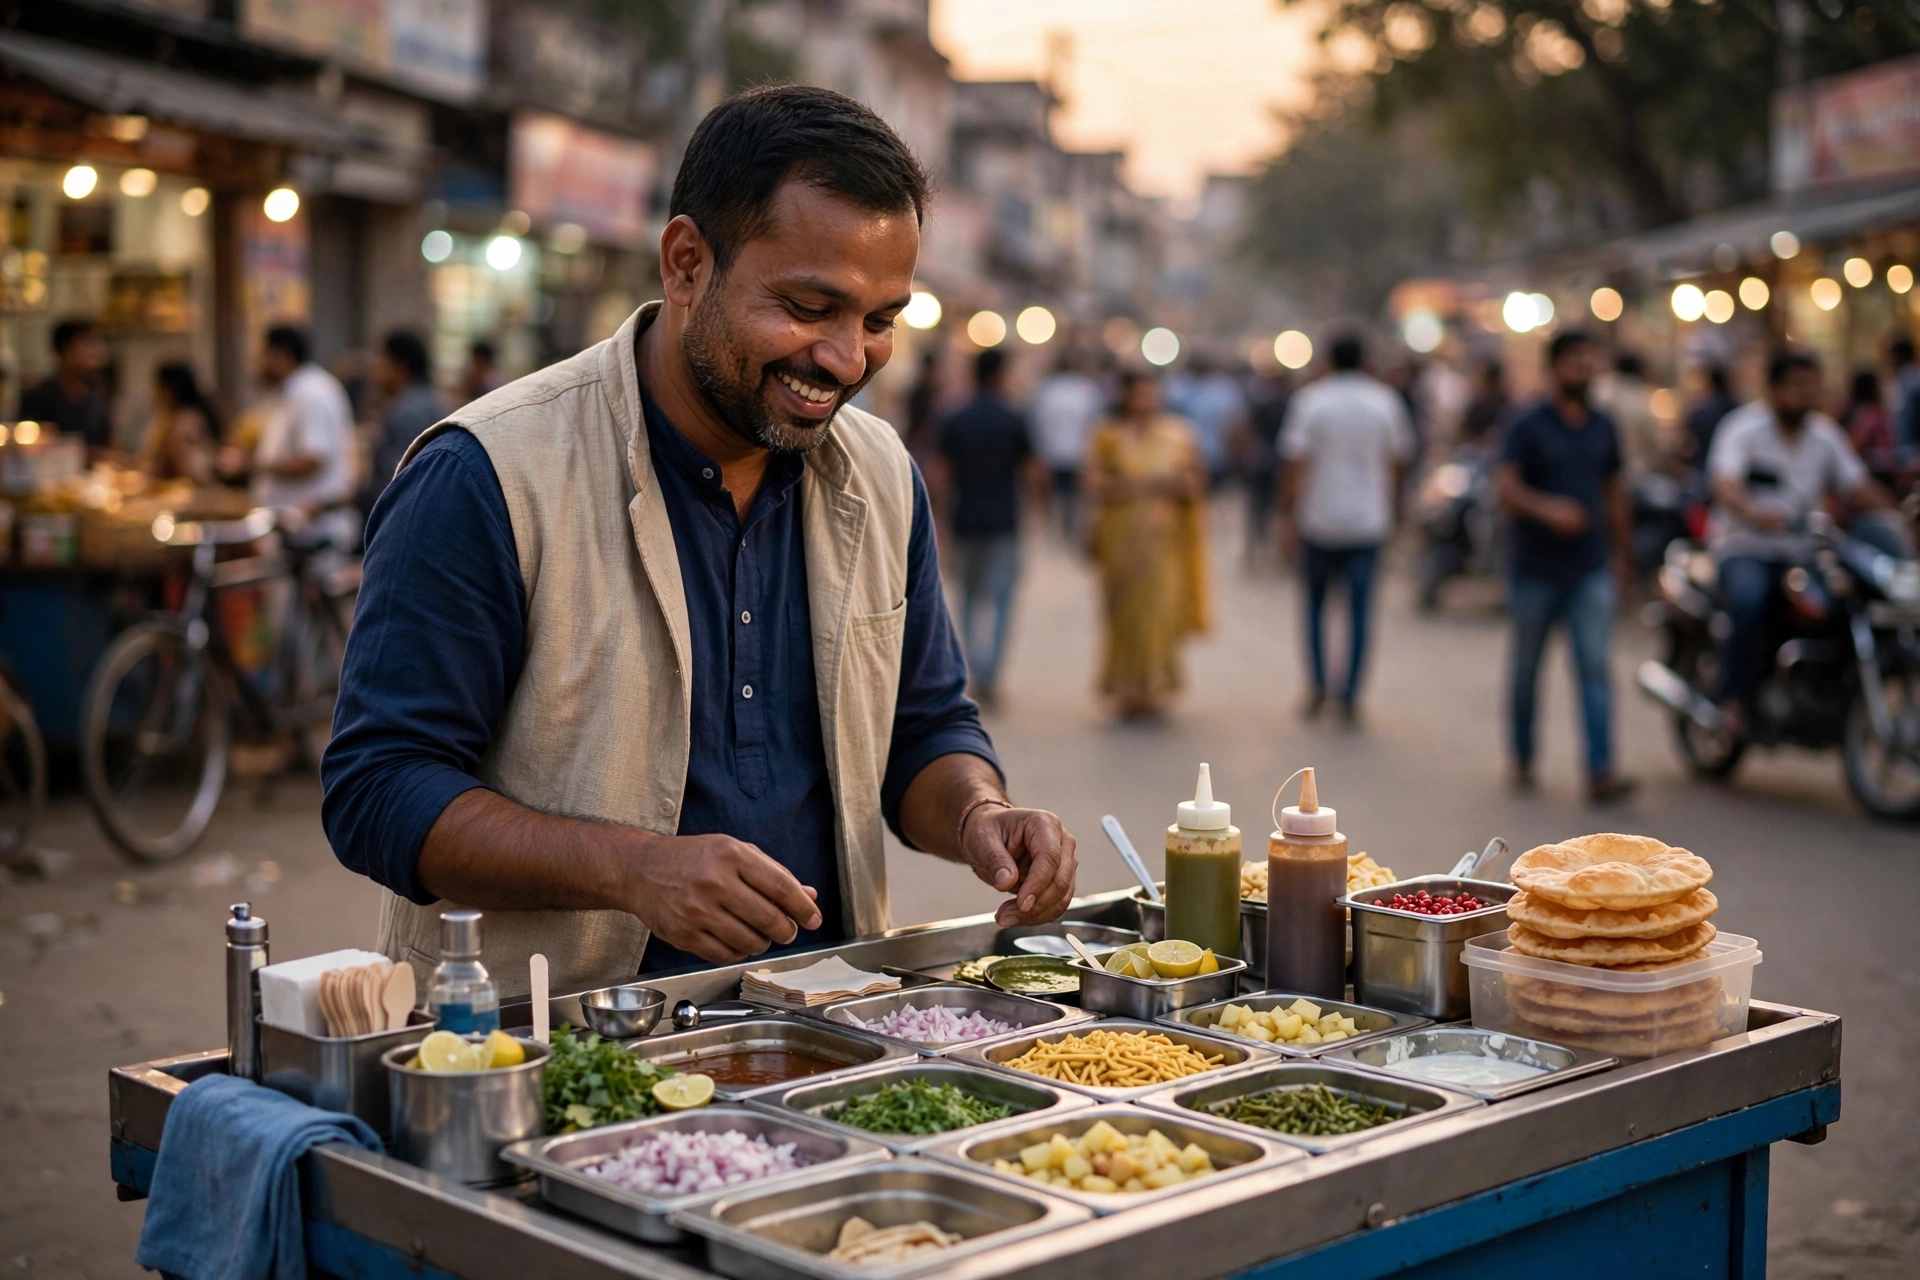
Eligibility
“Any individual with a small business plan” — for manufacturing, trading, services, allied agriculture. For non-corporate, non-farm micro/small enterprises.
How to Apply
Method 1: Any bank/NBFC/MFI branch. Method 2: www.udyamimitra.in online. No official document list — banks decide.
No Agents — Fraud Warning
mudra.org.in: “No agents or middlemen engaged by MUDRA.” Anyone claiming to be an agent is a fraud. Application is free.
Lenders
- Commercial Banks
- RRBs
- Small Finance Banks
- Cooperative Banks
- MFIs, NBFCs
Official Stats
PIB (8 Apr 2025): 52.37 cr loans, ₹33.65 lakh cr. Shishu 78%, Kishore 20%, Tarun 2%. ~70% to women; ~50% SC/ST/OBC.
FAQs
Q1: Launched when?
A: 8 April 2015.
Q2: Loan amounts?
A: Shishu ₹50K; Kishore ₹5L; Tarun ₹10L; Tarun Plus ₹20L.
Q3: Everyone gets ₹20L?
A: No — Tarun Plus only, after repaying Tarun.
Q4: Subsidy?
A: No permanent subsidy.
Q5: Interest rate?
A: Not fixed — lender decides per RBI norms.
Q6: Collateral?
A: No — CGFMU guarantee.
Q7: Does MUDRA lend directly?
A: No — refinance institution.
Q8: Where to apply?
A: Bank branch or udyamimitra.in.
Q9: Agents?
A: None exist — fraud warning.
Q10: Eligible who?
A: Anyone with a business plan.
Q11: Tarun Plus since?
A: 24 Oct 2024.
Q12: CGFMU?
A: Guarantee fund, 2016.
Q13: For farming?
A: Not direct farming — allied activities yes.
Q14: Which banks?
A: Commercial, RRB, SFB, Cooperative, MFI, NBFC.
Q15: “Funding the Unfunded”?
A: Scheme motto.
Q16: Documents?
A: No official list — bank decides.
Q17: Processing fee?
A: Unverified — ask bank.
Q18: Tenure?
A: “Flexible terms” — bank decides.
Q19: Women?
A: Yes — ~70% loans to women.
Q20: JanSamarth?
A: Portal for 15 credit schemes.
Q21: Govt site?
A: No — GramSuvidha is private.
Q22: Category difference?
A: Amount only.
Q23: Existing business?
A: Yes — new or running.
Q24: 2020-21 relief?
A: One-year COVID relief, ended.
Q25: Best info source?
A: mudra.org.in or bank.
Shishu Category: In Detail
Shishu is the smallest category — loans up to ₹50,000. It is for those starting a brand-new venture or running a very small operation. Per official data, 78% of all Mudra loans are in the Shishu category — making it the most-used segment.
By amount, ₹11.74 lakh crore has been sanctioned under Shishu (as on 21 March 2025). This shows small loans collectively create massive impact.
Shishu is especially popular among women and SC/ST/OBC communities — about 70% of loan accounts are in women’s names.
Kishore Category: In Detail
Kishore (spelled “Kishor” in PIB) covers ₹50,000 to ₹5 lakh. It is for entrepreneurs whose business is already running and who want to expand — buying new machinery, extending a shop, or stocking more inventory.
20% of Mudra loans by number are Kishore. By amount, ₹13.61 lakh crore sanctioned — the highest amount among all categories.
Tarun Category: In Detail
Tarun offers ₹5 lakh to ₹10 lakh for larger expansion — setting up a factory, opening a big showroom, or starting an operation with multiple employees.
Only 2% of Mudra loans are Tarun by number, but the amount is ₹8.27 lakh crore. This category is the gateway to Tarun Plus — only after repaying a Tarun loan does one qualify for ₹20 lakh.
How MUDRA’s Refinance Model Works
Understanding the money flow is important. MUDRA Ltd. is a refinance institution — it doesn’t hand you cash directly. Instead:
- You take a loan from a bank/NBFC/MFI
- That institution takes refinance from MUDRA
- This removes banks’ hesitation in giving small loans
That’s why you apply at a bank branch, not a MUDRA office.
Member Lending Institutions: Full List
Per PIB (March 2026), Mudra lenders are called Member Lending Institutions:
- Scheduled Commercial Banks — all public and private banks
- Regional Rural Banks (RRBs)
- Small Finance Banks
- Cooperative Banks
- MFIs — Microfinance Institutions
- NBFCs
Mudra Yojana in Numbers (Detailed)
PIB release 8 April 2025 (PRID 2119954), data as on 21 March 2025:
- 2015-16 (first year): 3.49 cr loans, ₹1.37 lakh cr
- Total (2015-2025): 52.37 cr loans, ₹33.65 lakh cr
- Growth: 15x rise in loan count over 10 years
Category-wise amount split:
- Shishu: ₹11.74 lakh cr (78% of loan count)
- Kishore: ₹13.61 lakh cr (20%)
- Tarun: ₹8.27 lakh cr (2%)
- Tarun Plus: ₹3,190 cr (new category)
Social impact: ~68-70% accounts in women’s names; ~50% to SC/ST/OBC borrowers — showing reach to underserved sections.
udyamimitra.in: Online Application Portal
www.udyamimitra.in is the official online portal named on mudra.org.in. Here you can:
- Apply online for a Mudra loan
- Find your nearest bank branch
- Track application status
Per PIB (March 2026), the JanSamarth portal also hosts 15 credit-linked schemes with self/assisted application.
Fraud Methods and Protection
mudra.org.in carries an official warning: MUDRA has no agents. Fraudsters typically:
- Pose as “MUDRA agents”
- Demand money/fees for getting a loan
- Make you fill fake forms
- Send fake links on WhatsApp/SMS
Protection: Visit only a bank branch or apply yourself on udyamimitra.in. Mudra application is free — refuse anyone asking for money and report to police/cyber cell.
Launch History and Context
PM Mudra Yojana was launched on 8 April 2015 by the Prime Minister as part of a broader financial-inclusion push. It rests on three pillars announced together: Banking the Unbanked (Jan Dhan accounts), Securing the Unsecured (Jan Suraksha insurance schemes), and Funding the Unfunded (Mudra loans). Together, these aimed to bring India’s informal micro-entrepreneurs into the formal financial system.
In its first year (2015-16), the scheme sanctioned 3.49 crore loans worth ₹1.37 lakh crore. Ten years later, cumulative sanctions reached 52.37 crore loans and ₹33.65 lakh crore — a fifteen-fold rise in loan count, per the PIB release of 8 April 2025.
Budget 2024-25: The Tarun Plus Announcement
The Tarun Plus category was announced in the Union Budget 2024-25 presented on 23 July 2024. The Budget proposed raising the Mudra loan limit to ₹20 lakh for entrepreneurs who had “availed and successfully repaid” Tarun loans. This took effect on 24 October 2024, per PIB. The Credit Guarantee Fund for Micro Units (CGFMU) coverage was simultaneously extended to these higher-value loans, keeping them collateral-free.
Working Capital: How Interest Works
For borrowers using the working-capital facility (as opposed to a term loan), PIB notes a borrower-friendly rule: interest is charged only on money held overnight by the borrower. This means if you draw funds during the day for business use and return them the same day, the interest burden is minimal — a design meant to suit the cash-flow patterns of tiny trading and service businesses.
FY 2024-25 Provisional Data
Per mudra.org.in (updated 29 November 2024), provisional figures for FY 2024-25 show 3,02,03,243 loans sanctioned, with ₹2,89,538.34 crore sanctioned and ₹2,82,407.41 crore disbursed. The high disbursement ratio indicates most sanctioned loans actually reached borrowers.
What the Scheme Does NOT Cover
To avoid confusion, these are explicitly not part of PMMY per official sources:
- Direct farming loans — the scheme covers non-farm enterprises and allied activities only
- Large corporate borrowers — only non-corporate micro/small units
- Fixed interest rates — rates are lender-determined under RBI guidelines
- Subsidies — no ongoing subsidy exists
- Agent-assisted applications — MUDRA engages no agents; applications are free
More FAQs
Q26: What was the first-year performance?
A: 3.49 crore loans, ₹1.37 lakh crore (2015-16).
Q27: When was the ₹20 lakh limit announced?
A: Budget 2024-25 (23 July 2024); effective 24 Oct 2024.
Q28: How does working-capital interest work?
A: Charged only on overnight holdings.
Q29: What are the three financial-inclusion pillars?
A: Banking the Unbanked, Securing the Unsecured, Funding the Unfunded.
Q30: Is there really no agent system?
A: Correct — mudra.org.in explicitly warns against fraudsters posing as agents.
Who Exactly Qualifies: Business Types
Per official definition, three main sectors are covered: manufacturing (small factories, handicrafts, food processing, tailoring, furniture), trading (shops, wholesale/retail, vegetable vending, kirana stores), and services (salons, repair shops, tuition centres, transport). Allied agricultural activities — dairy, poultry, beekeeping, fisheries — also qualify. Direct crop farming does not; that falls under KCC (Kisan Credit Card).
Q31: What are the three inclusion pillars?
A: Banking the Unbanked (Jan Dhan), Securing the Unsecured (Jan Suraksha insurance), Funding the Unfunded (Mudra).
Links
Disclaimer: GramSuvidha is a private portal, not a government site. Based on mudra.org.in and PIB — confirm before applying.